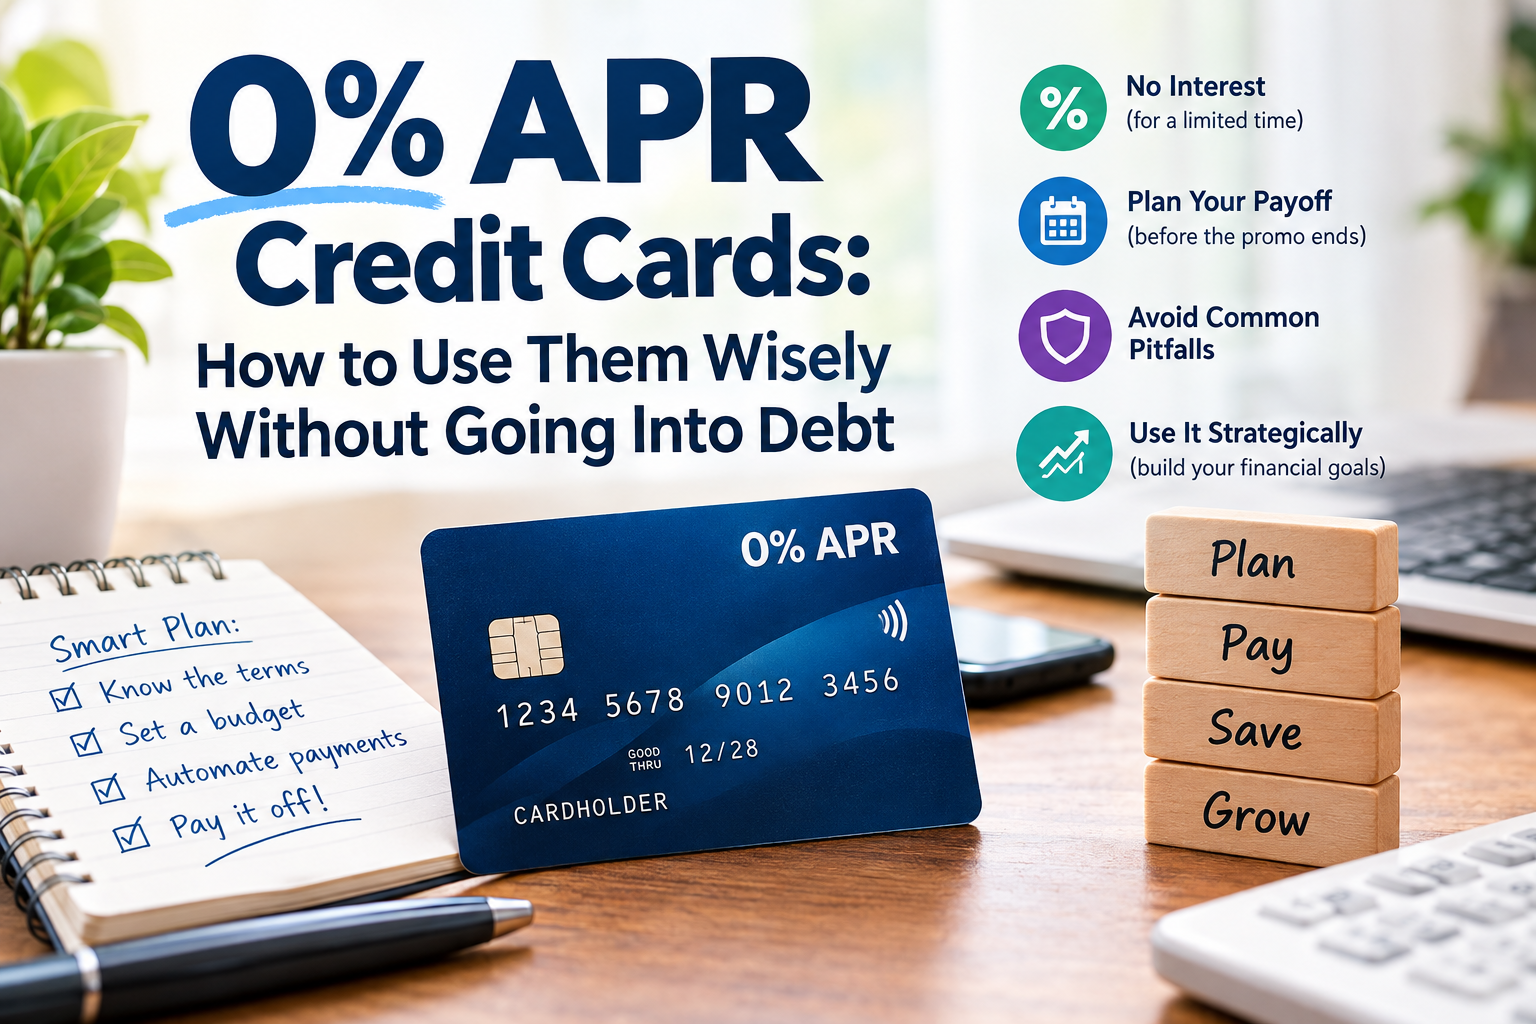

A 0% introductory APR credit card can be a remarkably effective financial tool, allowing you to finance a major purchase or pay off existing high-interest balances without accumulating interest charges during a set promotional window.
However, these cards frequently turn into an unexpected debt trap for cardholders who misunderstand how the promotional terms operate and what occurs the moment the offer expires. This guide outlines how 0% APR offers work, the specific pitfalls to steer clear of, and how to use them strategically rather than accidentally.
Purchase APR vs. Balance Transfer APR: Understanding Both Offers
Some cards offer 0% APR exclusively on new purchases, others apply it only to balance transfers, and several provide it on both, often with differing promotional timelines for each feature.
Confirming the exact type of 0% offer a card provides is critical before applying. A card featuring 0% strictly on balance transfers will not help you buy a major appliance interest-free, and vice versa. Always check the card’s specific Schumer box and terms, rather than just the headline marketing, to see what qualifies and for how long.
How the Promotional Window Actually Works
The 0% timeframe begins on the day your account is approved and opened, not from your first purchase or transfer date. Delaying your spending effectively reduces your available interest-free months.
Most introductory windows span 12 to 21 months, often determined by your overall credit profile. Once the promotional period concludes, any unpaid balance begins accruing interest at the card’s regular ongoing APR. On standard cards, this interest applies only to whatever balance remains going forward, rather than being retroactively calculated on the original starting balance.
| Promotion Type | How Interest Applies After Expiration | Overall Risk Level |
|---|---|---|
| Standard 0% Intro APR | Standard APR applies strictly to the remaining balance going forward | Lower Risk |
| Deferred Interest Promotion | Full retroactive interest charged from purchase date if not paid 100% | High Risk if Misunderstood |
The Crucial Difference: True 0% APR vs. Deferred Interest
This distinction represents one of the most critical and misunderstood concepts in retail financing. With a true 0% APR card, if you have a leftover balance of $200 when the promo expires, you only pay interest on that remaining $200.
Conversely, deferred interest offers—common with retail store financing and furniture store credit cards—operate under severe terms: if you owe even $1 by the deadline, the bank retroactively charges full interest on the entire original balance dating back to the day you bought it. This unexpected bill blindsides many buyers, making it essential to confirm your agreement structure upfront.
Formulating a Realistic Payoff Strategy
Before charging a large expense or transferring debt, take your total balance and divide it by the number of months in the promotional window. This calculation yields your required fixed monthly payment to reach a zero balance before standard interest begins.
Setting up automated monthly transfers for this exact amount—rather than making manual payments or paying only the minimum due—ensures you extract 100% of the financial benefit without leaving an expensive leftover balance.
What Causes You to Lose the Promotional Rate Early?
Most card issuers include terms allowing them to terminate your 0% promotional rate immediately if you make a single late payment, reverting your balance to the standard (and often penalty) APR. Paying on time throughout the promotional period is non-negotiable; setting up automatic minimum payments provides an essential safety net against accidental late fees.
Situations Where a 0% APR Card Makes Good Sense
- Financing a planned essential purchase (like home repairs or appliances) that you have budgeted to pay off completely within the promo window.
- Consolidating high-interest credit card debt through a balance transfer, provided the transfer fee (typically 3%–5%) is far lower than your existing interest costs.
- Handling an unexpected emergency expense (such as critical car repairs) without absorbing 25%+ interest charges while repaying.
- Covering temporary cash flow gaps for small business inventory that will be paid back quickly from upcoming revenue.
Scenarios Where a 0% Card Can Backfire
Using 0% APR promotions to purchase luxury goods you cannot truly afford—with the vague plan of “sorting out payments later”—is how consumers end up in serious credit card debt. The lack of interest creates a false sense of financial freedom, encouraging spending that would never make sense otherwise. Treating the promotion as an interest-free loan with a hard deadline is key to avoiding this trap.
Credit Score Impact of Applying for a 0% APR Card
Applying for a new card generates a temporary hard inquiry and reduces your average age of accounts, which can cause a small short-term score drop. However, if you use the card to pay down high-utilization debt across other cards, your overall credit utilization ratio improves significantly, usually creating a net positive score boost within a few months.
Tracking Your Promotional Expiration Deadline
Marking your calendar three months prior to the 0% expiration date gives you adequate time to accelerate payments if you have fallen behind schedule. You can also find your exact promotional end date directly on your monthly PDF statements or within your bank’s mobile app.
Integrating a 0% Card Into Your Monthly Budget
A 0% card succeeds when your calculated payoff amount is treated as a fixed monthly obligation, just like rent or utilities. Cardholders who build this repayment into their regular monthly budget consistently pay off their balances in full before interest rates kick in.
Earning Rewards on 0% APR Cards
Certain 0% cards also award cash back or points on purchases made during the introductory window, allowing you to accumulate rewards while avoiding interest fees. If everyday cash back matters to you, look for cards that combine rewards with promotional APR terms.
Why Some People Opt for a Fixed Personal Loan Instead
For consumers who struggle with the self-discipline required by a promotional deadline, a fixed-rate personal loan removes the cliff-edge risk entirely. With a personal loan, monthly payments and interest rates are locked for a multi-year term, eliminating the threat of a sudden 25%+ rate hike.
Reviewing Your Billing Statements Each Month
Reviewing your monthly statements ensures that payments are credited accurately, lets you verify your remaining balance against your payoff plan, and helps you catch any unexpected maintenance or service fees early.
Asking for a Promotional Rate Extension
If you approach the end of your promotional window with a modest remaining balance, call your card issuer. Issuers occasionally provide retention offers, such as a short temporary rate reduction, for customers in good standing who reach out proactively.
Fitting 0% Cards Into Your Emergency Fund Strategy
While a 0% card can help absorb unexpected emergency bills, it should complement—never replace—a genuine liquid savings fund. Depending exclusively on promotional credit leaves you vulnerable if an emergency arises when you do not qualify for promotional terms.
Practical Rules for Responsible Promotional Financing
When handled with care, 0% APR financing meaningfully strengthens your financial health by completely removing interest expenses. However, the savings depend entirely on strict adherence to your payoff timeline and automating your monthly contributions.
Keeping Perspective on Your Overall Financial Health
A 0% credit card is merely one financial tool. Its value is highest when applied to clear, specific objectives, rather than relied upon as an ongoing substitute for living within a sustainable monthly budget.
Final Thought
The ideal result of using a 0% APR credit card is simple: a fully cleared balance with zero interest paid. Setting up disciplined repayment habits ensures you reach that exact outcome.
Frequently Asked Questions (FAQs)
Does a 0% APR mean the card has no fees at all?
No. The 0% rate applies strictly to interest. Other standard fees—such as balance transfer fees (often 3% to 5%), late payment fees, and annual fees—still apply as outlined in the card agreement.
What happens if I pay off most, but not all, of the balance before the promo ends?
On a standard 0% APR card, interest begins accruing only on the remaining unpaid portion going forward. However, on a deferred interest card, any unpaid balance triggers retroactive interest on the entire original balance.
Can I get a new 0% APR card if I already have one open?
Yes, depending on your credit score and current debt load. However, submitting multiple credit card applications within a short timeframe results in hard inquiries that can lower your credit score.
The Bottom Line
A 0% APR credit card is a valuable financial instrument when paired with a clear, automated payoff schedule and a firm understanding of promotional terms. Calculating your required monthly contribution before charging an expense, setting up auto-pay, and verifying whether an offer uses standard or deferred interest ensures that a promotional card saves you real money rather than creating unnecessary debt.