
Selecting the wrong mortgage lender can cost you far more than a slightly higher interest rate—it can cause unexpected closing delays, surprise administrative fees at settlement, and unnecessary anxiety during one of the largest financial purchases of your life.
This guide explains how to compare mortgage lenders side-by-side, how to evaluate the standard Loan Estimate disclosure, and the specific questions that separate a dedicated loan officer from one who leaves you waiting.
Why Comparing Mortgage Lenders Matters More Than You Think
Research from government housing agencies repeatedly reveals that borrowers who obtain just one quote pay significantly more over their loan term than those who compare three to five competing institutions.
Interest rate spreads for the identical borrower profile, quoted on the exact same day, regularly vary by 0.25% to 0.50% between lenders. On a $400,000 mortgage, that difference adds up to tens of thousands of dollars in interest over 30 years. Yet many first-time buyers simply accept the first lender recommended by their real estate agent without checking alternatives at competing regional banks, credit unions, or independent mortgage brokers.
Understanding the Loan Estimate Document
Federal regulations mandate that all lenders provide a standardized three-page Loan Estimate within three business days of receiving your completed application. Because every lender uses this identical format, it serves as your most reliable comparison tool.
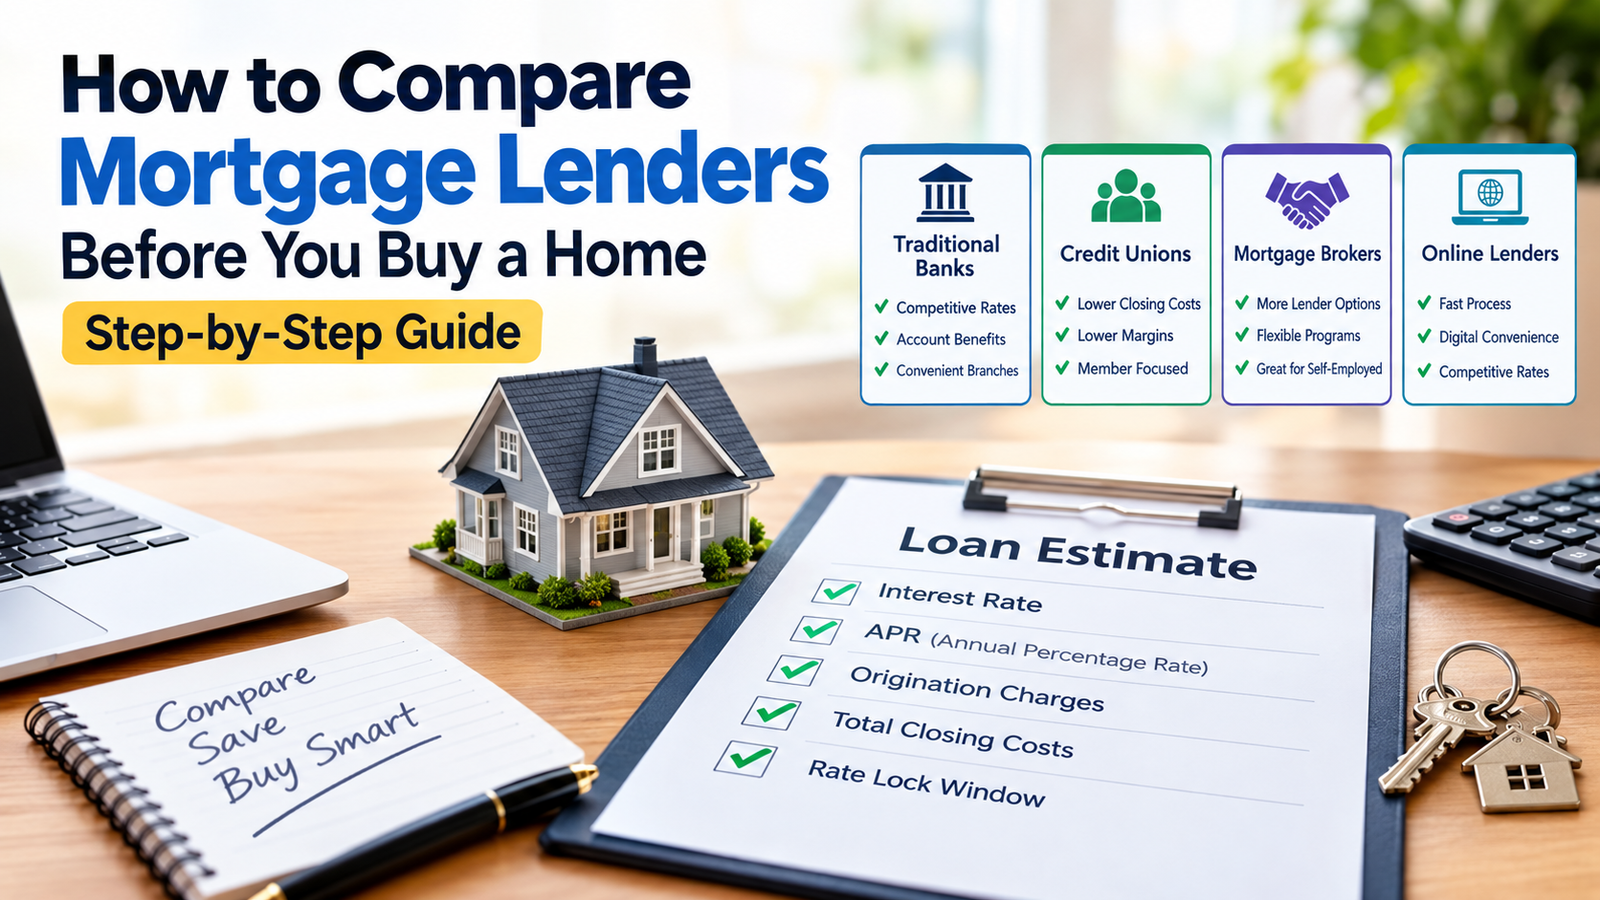
Page 1 details loan terms, projected monthly payments, and estimated closing cash requirements. Page 2 itemizes closing fees divided into loan charges and third-party services. Page 3 provides total five-year loan costs and the Annual Percentage Rate (APR)—the truest single benchmark because it rolls both interest and upfront fees into one figure. Focus closely on Section A (origination charges) on page 2, where lenders disclose their direct fees and margin.
| Key Comparison Factor | Where It Appears | Why It Matters to You |
|---|---|---|
| Note Interest Rate | Loan Estimate, Page 1 | Directly determines your principal & interest monthly payment |
| Annual Percentage Rate (APR) | Loan Estimate, Page 3 | Reflects the true borrowing cost including lender fees |
| Origination Charges | Loan Estimate, Page 2 (Section A) | Lender’s direct processing, underwriting fees, and points |
| Total Closing Costs | Loan Estimate, Page 2 | Determines the out-of-pocket cash required on closing day |
| Rate Lock Window | Loan Estimate or Lock Agreement | Protects your rate from market spikes before settlement |
Banks vs. Credit Unions vs. Brokers vs. Online Lenders
Traditional retail banks often offer account-relationship rate reductions for existing deposit customers, along with the convenience of banking in one place. Credit unions frequently feature lower closing costs and lower margins due to their member-owned, not-for-profit model, though membership criteria apply.
Independent mortgage brokers shop wholesale rates across dozens of wholesale lenders, which helps buyers with complex self-employment income or lower credit scores. Online lenders and fintech platforms process documentation rapidly via streamlined mobile portals, though individual personalized guidance can vary.
Key Questions to Ask Every Lender Before Committing
- What is your average closing timeline from application to funding, and what causes potential delays?
- Is my rate locked today, for how many days, and what are the fees if closing extends past the lock date?
- Do you service this mortgage in-house after settlement, or will the servicing rights be transferred?
- Can you provide a complete list of required financial documentation upfront rather than piecemeal?
- Are there any early prepayment penalty clauses if I refinance or sell within the first few years?
Why You Should Submit All Loan Applications Within a Tight Window
Credit scoring algorithms bundle all mortgage-related inquiries within a 14 to 45-day window as a single hard inquiry, recognizing that borrowers are rate-shopping. Submitting your applications within a focused two-week window protects your credit score and ensures you evaluate offers under identical market interest rate conditions.
Identifying Junk Fees and Unnecessary Lender Charges
Certain lenders pad Section A charges with redundant line items like document preparation, administrative, processing, and underwriting fees. While standard underwriting costs are normal, stacked overlapping charges are a signal to question the breakdown. Lenders eager to secure your business often reduce or waive discretionary origination fees when shown a lower competing Loan Estimate.
How to Handle Real Estate Agent Lender Recommendations
Real estate agents regularly recommend lenders known for closing on time, which is valuable for protecting contract deadlines. However, an agent’s preferred contact is not always the lowest-priced option. Real estate agents are not legally paid to endorse specific lenders, so feel free to include their contact as one of your multiple quotes rather than your only bid.
Pre-Approval vs. Pre-Qualification: Key Differences
Pre-qualification is an informal estimate based on self-reported finances without document verification. A verified pre-approval requires an underwriter to review actual W-2s, tax returns, and bank statements, yielding a formal conditional commitment letter that home sellers take seriously in competitive bidding environments.
Timing Your Mortgage Rate Lock
After choosing a lender, you typically lock your interest rate for 30, 45, or 60 days. A rate lock insulates you if market interest rates increase before closing. Selecting a lock duration that easily accommodates your purchase closing date avoids the expense of paying for rate lock extensions.
Why Loan Officer Responsiveness Is a Critical Signal
The stated interest rate matters, but the responsiveness of the individual handling your file directly dictates whether closing happens smoothly. Pay attention to how quickly loan officers return emails and whether they proactively explain requirements.
Ask prospective lenders how many files their underwriting team manages each month and what their current average time from application to funding is. High pipeline backlogs can cause missed contract deadlines, which can carry financial penalties under your purchase agreement.
How Your Down Payment Affects Lender Comparisons
Your down payment percentage influences loan pricing, loan program eligibility, and private mortgage insurance (PMI). When lining up quotes, make sure every lender uses identical down payment figures and the exact same loan program (e.g., comparing 5% down conventional to 5% down conventional), ensuring you make a true apples-to-apples comparison.
Understanding Underwriting Overlays Across Lenders
In addition to baseline agency guidelines (Fannie Mae, Freddie Mac, or FHA), individual lenders often apply their own stricter internal criteria, known as “lender overlays.” For instance, a lender might require a 660 credit score for an FHA loan even though federal rules allow lower scores. Asking about overlays helps explain why one lender might decline an application while another approves it readily.
Accounting for Seller Concessions and Rate Buydowns
In buyer-favorable markets, home sellers often offer credits to fund temporary rate buydowns (such as a 2-1 buydown) or purchase permanent discount points. When evaluating lenders on transactions with seller credits, verify that each lender structures the concession identically on their Loan Estimate so you compare true effective rates across all years.
Loan Servicing and Long-Term Account Management
Many mortgage companies sell loan servicing rights to secondary servicers shortly after closing. While this is standard practice and leaves your original loan terms unchanged, it means the originating lender’s customer portal may not be who you make payments to long-term. If retaining in-house servicing matters to you, verify whether the institution retains servicing before committing.
Frequently Asked Questions (FAQs)
How many mortgage lenders should I get quotes from?
Comparing three to five lenders is optimal. This provides a clear cross-section of market pricing without the diminishing returns of managing dozens of applications.
Does shopping multiple mortgage lenders hurt my credit score?
No. Credit scoring models treat multiple mortgage inquiries within a standard 14 to 45-day window as a single credit check, minimizing the impact on your credit score.
Can you negotiate closing fees with a mortgage lender?
Yes. Discretionary origination, processing, and underwriting fees in Section A are frequently negotiable when you present a competing lender’s more favorable Loan Estimate.
The Bottom Line
Comparing mortgage lenders properly requires collecting official Loan Estimates from three to five institutions within a tight two-week window, evaluating APR and Section A origination charges, and verifying underwriting turn times. Taking a few days to shop competitors routinely saves tens of thousands in long-term interest and prevents costly surprises on closing day.