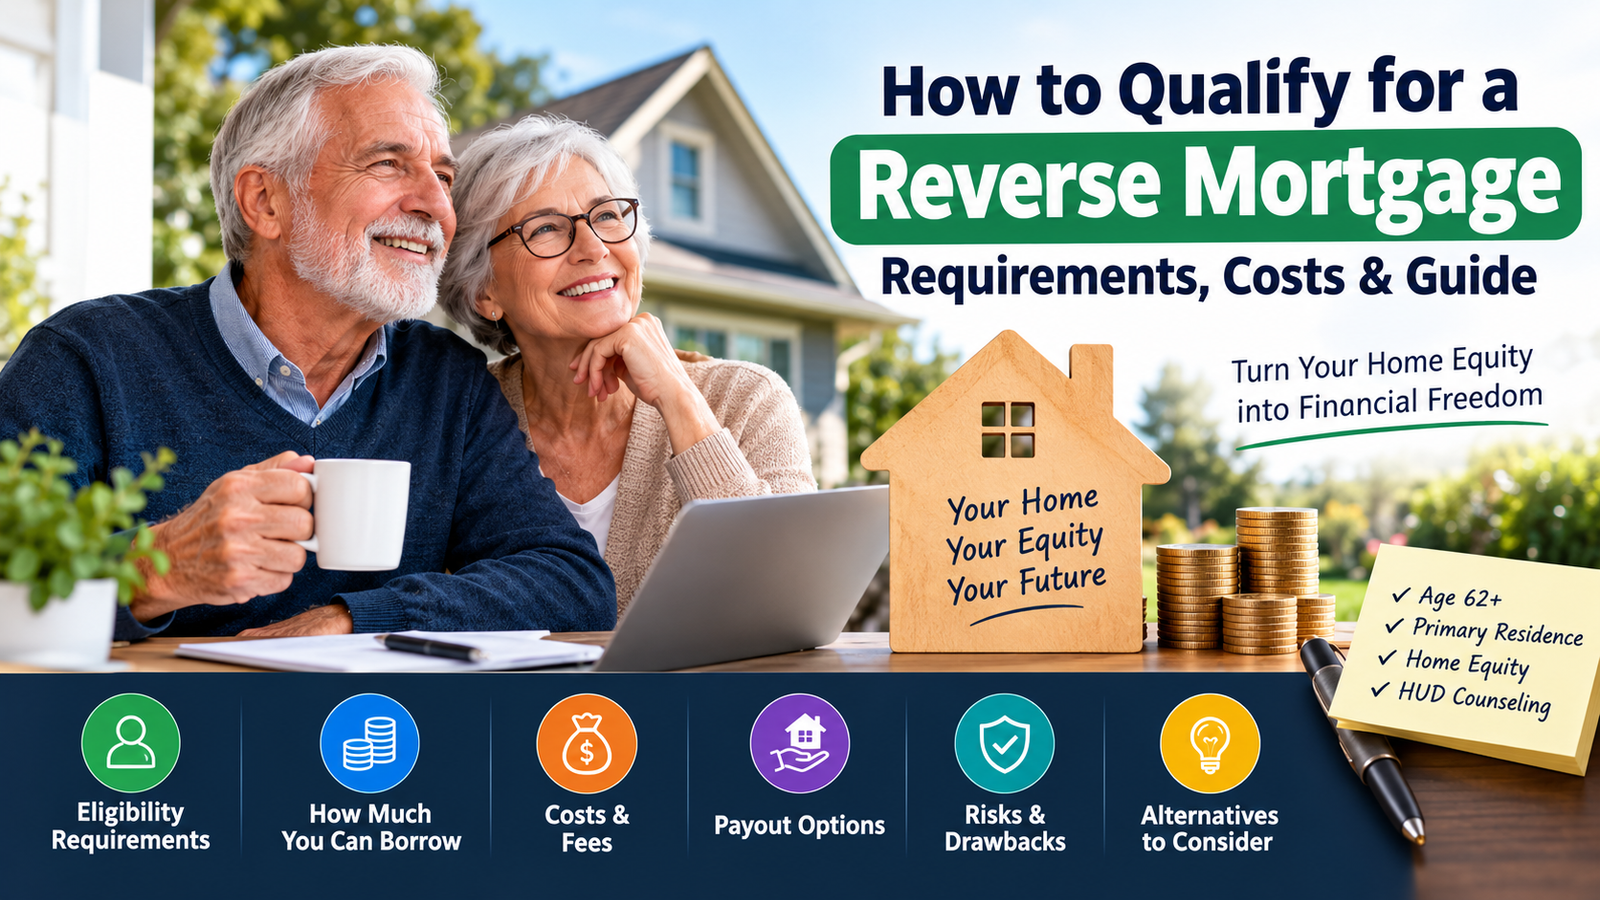

A reverse mortgage allows senior homeowners to convert accumulated property equity into spendable funds without the burden of monthly loan payments. However, it remains one of the most misunderstood financial vehicles available, carrying both genuine retirement advantages and substantial risks that demand careful scrutiny before signing.
This comprehensive guide explains how reverse mortgages operate, who qualifies under federal rules, true closing costs, how payouts are disbursed, and when this loan structure makes sense compared to alternative financing options.
How a Reverse Mortgage Functions
The most common reverse mortgage is the Home Equity Conversion Mortgage (HECM), insured by the federal government via the Federal Housing Administration (FHA). It allows homeowners aged 62 or older to borrow against their property equity without making regular principal and interest payments to a bank.
Instead, the lender disburses money to the borrower—via an upfront lump sum, steady monthly installments, or an adjustable line of credit—while monthly interest compounds onto the loan balance over time. The mortgage matures and must be paid back when the last surviving homeowner permanently moves away, sells the house, or passes away. At that stage, the property is typically sold to satisfy the debt, with remaining equity going to the heirs.
Core Eligibility Requirements
- Age Threshold: The youngest titled homeowner on the deed must be at least 62 years of age.
- Primary Residence: The home must serve as your primary residence, lived in for the majority of the calendar year.
- Home Equity Level: You must own the house free and clear, or maintain a balance low enough to be cleared with the reverse mortgage funds.
- Financial Assessment: You must pass a financial assessment showing adequate income to pay ongoing property taxes, hazard insurance, and maintenance.
- Property Standard: Must meet FHA safety standards (single-family homes, FHA-approved condos, or 2–4 unit owner-occupied properties).
How Much Can You Actually Borrow?
The total amount you can access (the principal limit) depends on a government formula evaluating the age of the youngest homeowner, prevailing interest rates, and the home’s appraised market value up to the FHA lending limit.
Older borrowers qualify for a higher percentage of equity because their life expectancy indicates a shorter loan duration. Lower interest rate environments also increase borrowing limits, as less projected future interest needs to be set aside against the property.
| Underwriting Variable | Effect on Available Borrowing Capacity |
|---|---|
| Older Borrower Age | Increases available percentage of home equity |
| Lower Market Interest Rates | Expands the available borrowing capacity |
| Higher Appraised Property Value | Increases total loan amount (up to federal limit) |
| Existing Mortgage Balance | Must be paid off first, reducing net cash to borrower |
The Real Upfront and Ongoing Costs
Reverse mortgages carry higher closing costs than standard home equity loans. Typical fees include an upfront lender origination fee (capped by federal formula based on home value), an upfront FHA mortgage insurance premium (MIP), settlement charges (appraisals, title insurance, recording fees), and ongoing annual mortgage insurance fees.
While these expenses are almost always financed directly into the loan rather than paid out of pocket, interest compounds on the entire balance. Consequently, your loan balance grows larger each month instead of shrinking over time.
Common Uses for Reverse Mortgage Funds
Retirees deploy reverse mortgage proceeds for varied financial needs: supplementing monthly Social Security or pension income, paying off existing forward mortgages to eliminate monthly bills, funding home modifications to age in place, or establishing a standby line of credit. The unused portion of a HECM credit line actually grows over time at the same compounding rate as the loan, providing expanding borrowing power as retirees age.
Genuine Risks and Drawbacks to Consider
Because loan balances grow as interest compounds, a reverse mortgage significantly diminishes the equity left behind for heirs. Furthermore, borrowers remain legally obligated to pay annual property taxes, hazard insurance, and property upkeep. Failing to pay taxes or insurance can trigger loan default and foreclosure. Moving into assisted living for over 12 consecutive months also triggers the loan repayment deadline. Non-borrowing spouses not listed on the deed face specific residency restrictions that must be reviewed during counseling.
Non-Recourse Protection: A Critical Safeguard
Federally insured HECM loans feature strict non-recourse protections. This means neither the homeowner nor their heirs will ever owe more than the home’s fair market value at the time of sale. If compounding interest results in a loan balance exceeding the property value, the federal mortgage insurance fund absorbs the deficiency, protecting personal assets and estates from debt liability.
Important Alternatives to Compare First
- Home Equity Line of Credit (HELOC): Lower upfront fees and lower rates for seniors who can comfortably afford monthly interest payments.
- Downsizing: Selling a large family home and purchasing a smaller, single-story property frees up cash without incurring new debt.
- Cash-Out Refinancing: Works for retirees with steady retirement income who want a lump sum and prefer fixed monthly payments.
- Selling and Renting: Unlocks all equity immediately and removes property taxes, insurance, and maintenance responsibilities entirely.
The Mandatory HUD Counseling Session
Federal law mandates that all HECM applicants attend a confidential counseling session with an independent, HUD-approved housing counselor before submitting an application. The counselor reviews total fees, explains financial alternatives, and ensures borrowers understand ongoing property tax responsibilities without sales pressure from lenders.
How Loan Repayment Works for Heirs
When the borrower passes away, heirs typically receive 30 days (with extensions granted up to one year) to determine how to settle the estate. Heirs can choose to refinance the balance into a conventional mortgage to keep the home, sell the property and pocket the remaining equity, or allow the lender to sell the home with zero personal liability for any shortfall.
Choosing Between Lump Sum, Monthly Payouts, or a Credit Line
Adjustable-rate HECMs let borrowers choose their distribution method. A lump sum delivers immediate cash, but interest accrues on the full balance immediately. Tenure payments provide guaranteed monthly deposits for life as long as you reside in the house. A line of credit offers ultimate flexibility, drawing funds only when needed while the unused credit line continues to grow over time.
Comparing Multiple Reverse Mortgage Lenders
While FHA regulations govern loan limits, lender origination fees, interest margins, and third-party closing costs vary between banks. Comparing quotes from at least two or three approved lenders ensures you secure the lowest administrative margins and maximize net cash proceeds.
How Real Estate Value Trends Affect Equity
Because loan balances grow over time, local housing appreciation plays a major role in preserving inheritance. In appreciating real estate markets, property values can rise faster than loan interest, leaving meaningful equity for family members. In stagnant markets, equity diminishes faster, though non-recourse rules guarantee heirs never inherit debt.
Frequently Asked Questions (FAQs)
Will my heirs inherit debt from a reverse mortgage?
No. FHA HECM loans are strictly non-recourse. Heirs are never personally responsible for debt exceeding the home’s sale price, and they retain any remaining equity after the loan balance is cleared.
Can a homeowner lose their house with a reverse mortgage?
Yes. If you fail to pay property taxes, hazard insurance, or maintain the physical property, or if you vacate the home for more than 12 consecutive months (such as moving into nursing care), the lender can call the loan due and initiate foreclosure.
Is reverse mortgage interest tax-deductible annually?
No. Reverse mortgage interest is only tax-deductible when it is actually paid, which typically occurs when the property is sold and the loan is satisfied in full at the end of the loan term.
The Bottom Line
A reverse mortgage provides a legitimate financial safety net for seniors with significant home equity seeking to supplement retirement income or eliminate monthly debt payments. However, closing costs are high, home equity diminishes over time, and keeping property taxes current is mandatory to prevent default. Evaluating options like downsizing or HELOCs, attending the required HUD counseling session, and discussing plans openly with heirs ensures this complex decision supports your retirement security.