
Purchasing a first home involves an extensive checklist, and homeowners insurance is a major line item that first-time buyers frequently underestimate—both regarding real annual costs and how policy fine print dictates claim payouts following property damage.
This guide explains what a standard policy covers, how underwriters price risk, which coverage decisions genuinely protect your largest physical asset rather than simply fulfilling lender closing rules, and the common oversights that leave new buyers underinsured when emergencies strike.
Why Your Mortgage Lender Mandates Home Insurance
Because your house acts as collateral for the mortgage, lending institutions demand proof of property insurance prior to closing specifically to shield their financial investment, rather than purely for your personal protection.
Consequently, lenders establish minimum insurance floors—usually equal to the structure’s replacement value or the loan balance. Many first-time buyers assume this lender minimum is the ideal coverage level, whereas it actually functions as a baseline that often leaves your personal belongings, liability exposure, and true reconstruction costs underprotected.
Core Coverage Types in a Standard Policy
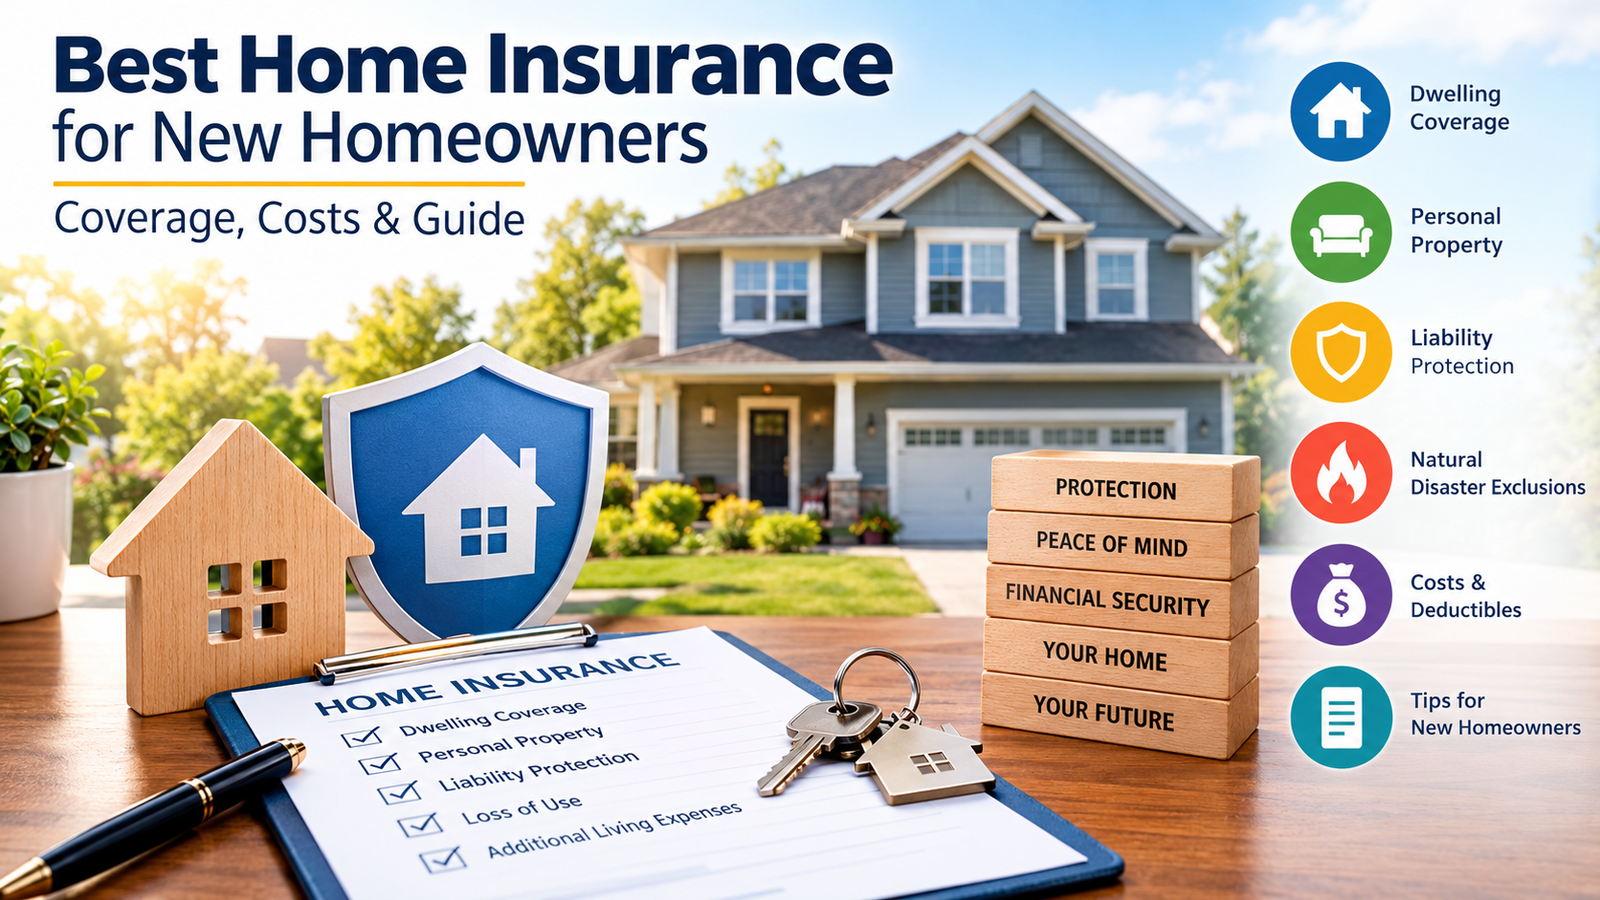
A standard HO-3 homeowners policy bundles several distinct protections: Dwelling coverage pays to repair or rebuild the physical structure; Other Structures covers detached garages, sheds, or fencing; Personal Property reimburses damaged or stolen furniture, electronics, and clothing; Loss of Use covers hotel and living expenses if the home becomes uninhabitable; Personal Liability covers legal defense and settlements if someone is injured on your property; and Medical Payments handles minor guest injury claims without fault disputes.
| Coverage Section | What It Specifically Protects | Standard Recommended Baseline |
|---|---|---|
| Dwelling Coverage (Coverage A) | The primary physical house structure | 100% estimated replacement cost |
| Other Structures (Coverage B) | Detached garages, sheds, exterior fences | 10% of dwelling limit |
| Personal Property (Coverage C) | Furniture, clothing, appliances, electronics | 50% to 70% of dwelling limit |
| Loss of Use (Coverage D) | Temporary apartment rent and displacement meals | 20% of dwelling limit |
| Personal Liability (Coverage E) | Third-party injury claims and legal defense | $300,000 to $500,000 minimum |
Replacement Cost vs. Actual Cash Value: A Crucial Distinction
Replacement cost coverage reimburses the actual cost to repair damage or replace property with brand-new materials of similar quality, without factoring in depreciation. In contrast, Actual Cash Value (ACV) deducts depreciation for age and wear.
Under ACV, a 12-year-old shingle roof damaged by hail is paid out based on its diminished current value, leaving the homeowner to fund a massive out-of-pocket gap to purchase a replacement. Choosing full replacement cost coverage carries a slightly higher premium but prevents severe financial shortfalls during major claims.
Standard Exclusions That Catch New Homeowners Off Guard
Standard homeowners insurance explicitly excludes flood damage, earth movement/earthquakes, sewer or drain backups (unless added by endorsement), and deferred maintenance wear. While buyers in federally designated high-risk flood zones are mandated by lenders to buy separate National Flood Insurance Program (NFIP) policies, buyers outside mapped flood plains frequently go uninsured, despite a significant percentage of flood losses occurring in moderate-to-low risk areas.
How Insurers Calculate Your Annual Premium
Insurance rates are based on your home’s estimated rebuild cost (which excludes land value), age of construction, roofing materials, distance to emergency fire services, regional storm frequency, and your credit-based insurance score. In addition, insurers review past claims filed on the property by previous owners via the Comprehensive Loss Underwriting Exchange (CLUE) database, meaning an address with multiple previous claims can carry higher rates regardless of your clean personal history.
Choosing the Right Deductible Structure
Increasing your standard policy deductible from $1,000 to $2,500 lowers your annual insurance bill. However, in regions prone to severe windstorms or hurricanes, insurers often enforce separate percentage-based storm deductibles (e.g., 2% to 5% of dwelling coverage). On a $400,000 dwelling limit, a 2% hurricane deductible equates to an $8,000 out-of-pocket expense before insurance coverage kicks in.
Practical Bundles and Available Policy Discounts
- Multi-Policy Bundles: Pairing your home and car insurance with one carrier delivers savings of 10% to 20%.
- Monitored Protective Systems: Smart smoke alarms, water leak sensors, and central-station security systems reduce premiums.
- Updated Infrastructure: Homes with new roofs, updated copper/PEX plumbing, and modern electrical panels receive lower risk ratings.
- Claims-Free History: Maintaining a clean record without minor claims keeps rating tiers low.
Documenting a Home Inventory: The Step Most Buyers Skip
Following a devastating house fire or tornado, recalling every belonging from memory is exceptionally difficult. Taking a quick 15-minute video walkthrough of your house—recording inside drawers, closets, tools, and electronics—along with saving receipts in cloud storage speeds up claims handling and guarantees you receive fair compensation for everything you owned.
How Claims History Follows Both the Home and You
Every insurance claim you file is tracked across the national insurance database and influences your rates across all insurers for five to seven years. Reserve insurance claims for catastrophic losses, paying minor repairs out-of-pocket when feasible, because small payouts can lead to cumulative rate hikes that exceed the original payout.
Working With an Independent Agent as a First-Time Buyer
Independent brokers represent multiple insurance providers and can compare your home profile against regional and national carriers simultaneously. While captive agents represent only one brand, independent agents can present multiple quotes side-by-side to find the best policy fit for your area.
Personal Umbrella Policies: Protection Beyond Standard Limits
A personal umbrella policy adds an additional $1 million or more in liability coverage above your underlying auto and home liability limits for a modest annual premium. For homeowners with savings, investments, or significant future income, umbrella coverage prevents a catastrophic personal injury lawsuit from seizing personal wealth.
How Escrow Accounts Handle Your Insurance Payments
Lenders routinely set up mortgage escrow accounts, collecting a portion of your annual insurance and property tax bills inside your monthly mortgage payment. When insurance rates rise at renewal, your mortgage servicer adjusts your monthly escrow payment upward to compensate, which explains why monthly mortgage bills can increase even on fixed-rate loans.
Reviewing Your Policy Annually, Not Just at Closing
Building material costs, labor rates, and physical property renovations change over time. Finishing a basement or remodeling a master bathroom increases your property’s total rebuild cost. Reviewing your policy limits annually ensures your dwelling coverage reflects current regional construction costs rather than outdated historical figures.
Steps to Take Immediately After an Insurance Loss
If your property suffers damage, capture detailed photos and video before starting cleanup. Make temporary repairs to prevent secondary water or weather damage (such as tarping a broken window), save contractor receipts, and maintain a written log of all communications with your insurance adjuster.
How Natural Disaster Trends Impact Pricing and Availability
In coastal regions or areas prone to wildfires and severe convective storms, carriers have tightened underwriting or exited regional markets entirely. Research home insurance availability during your property search contingency period to verify that the home can be insured affordably through standard carriers rather than through expensive state FAIR plans.
Frequently Asked Questions (FAQs)
Do I need flood insurance if my property is outside a designated flood zone?
It is strongly recommended. Standard homeowners policies exclude surface flooding entirely, and a significant portion of flood claims nationwide happen in moderate-to-low risk zones outside special flood hazard areas.
How much personal liability coverage should a new homeowner carry?
Most insurance advisors recommend a minimum of $300,000 to $500,000 in liability protection, supplemented by a personal umbrella policy for households with significant personal savings or real estate investments.
Will my home insurance premium rise every year without filing any claims?
Yes, premiums frequently increase due to rising local construction labor rates, lumber prices, and regional storm payouts across the insurance carrier’s overall book of business.
The Bottom Line
Homeowners insurance for a new buyer is much more than a routine closing document for the mortgage company—it is the vital safety net protecting your most significant investment. Selecting replacement cost coverage over actual cash value, understanding flood and storm exclusions, setting adequate liability limits, and creating a recorded video inventory ensure your coverage stands up when you need it most.