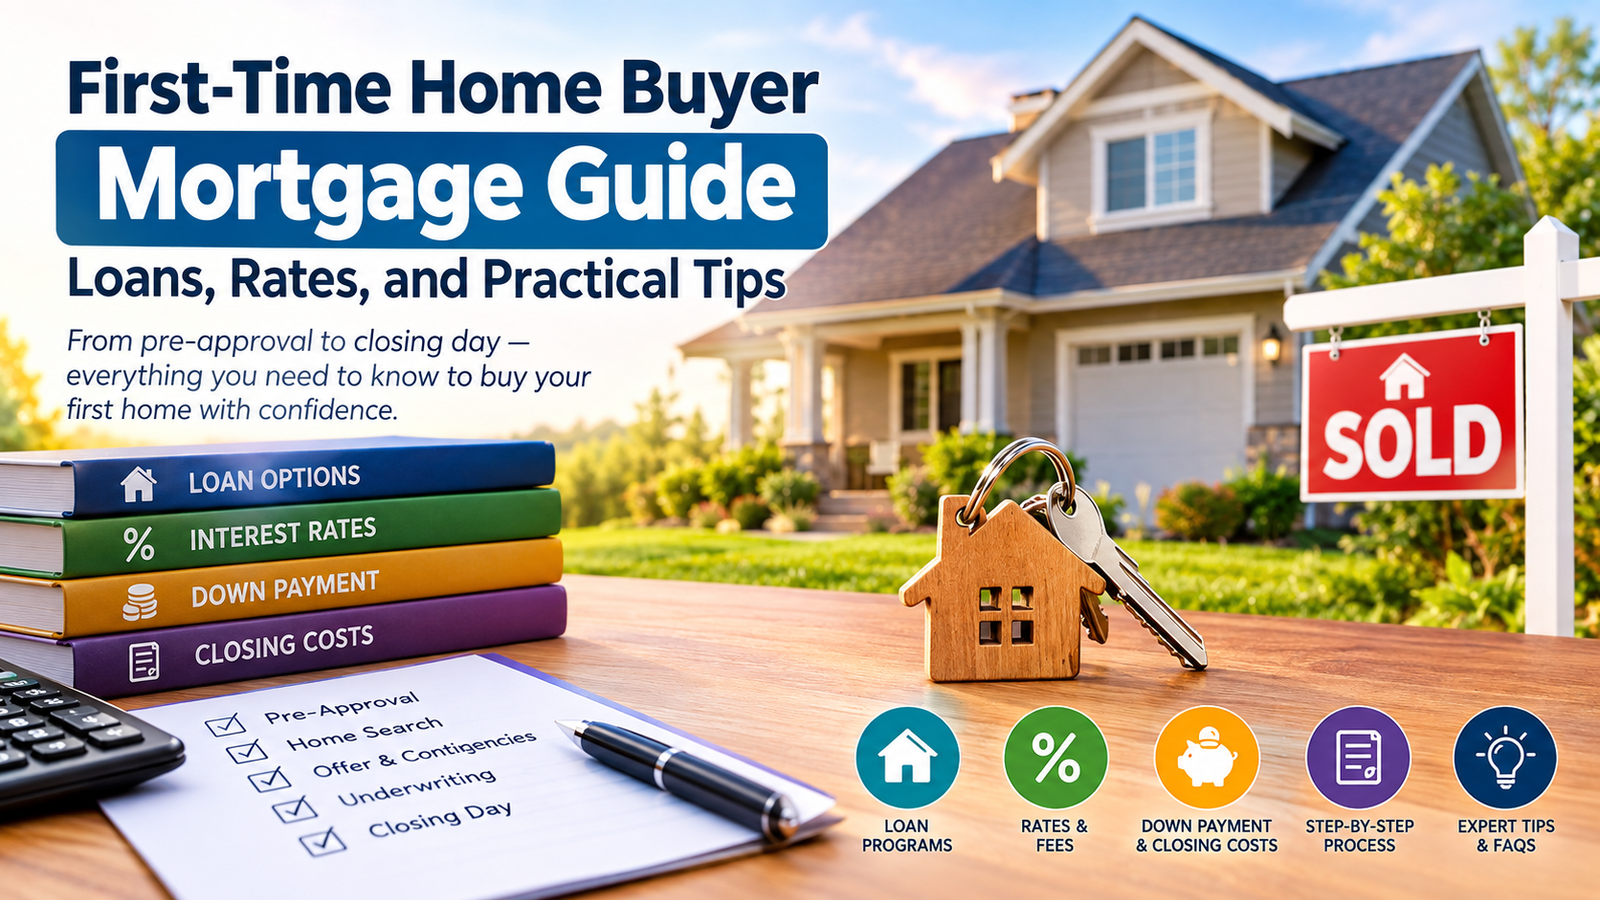

Purchasing your very first home requires navigating complex loan options, down payment rules, credit score minimums, and closing procedures that most buyers encounter simultaneously under strict contractual deadlines.
This step-by-step guide explains the entire first-time mortgage process in sequential order—from calculating what you can genuinely afford and selecting the right loan type, to understanding what happens on closing day—so you can buy your home with clarity and confidence.
Step 1: Understand What You Can Truly Afford
Lenders assess your borrowing power primarily through your debt-to-income (DTI) ratio—the percentage of your gross monthly earnings that covers existing debt obligations, including your estimated new mortgage payment. Most conventional loan programs cap DTI around 43% to 50%, though lower ratios secure more competitive interest rates and wider loan selections.
Beyond official lender approval limits, calculate your personal comfort level by factoring in local property taxes, homeowners insurance, HOA dues, ongoing repairs, and long-term retirement savings. The maximum loan amount a bank approves is rarely the amount you should comfortably spend.
Step 2: Select the Right Loan Program for Your Needs
First-time buyers can choose from various mortgage programs beyond standard financing. FHA loans permit down payments as low as 3.5% with flexible credit thresholds, though they require mortgage insurance premiums (MIP). VA loans provide zero-down-payment financing with no ongoing mortgage insurance for qualifying military veterans. USDA loans offer 0% down financing in eligible rural and suburban zones. Conventional loans with just 3% down are also widely available for first-time buyers, along with state-sponsored down payment assistance grants.
| Mortgage Program | Typical Minimum Down Payment | Key Defining Feature |
|---|---|---|
| Conventional Loan | 3% | PMI is removable once reaching 20% equity |
| FHA Loan | 3.5% | Flexible credit score thresholds for approval |
| VA Loan | 0% | Zero down payment, no monthly mortgage insurance |
| USDA Loan | 0% | Restricted to eligible rural and suburban territories |
Step 3: Get Pre-Approved, Not Merely Pre-Qualified
Pre-qualification relies on self-reported financial estimates, whereas a formal pre-approval involves an underwriter verifying your tax returns, bank accounts, pay stubs, and credit files to issue a written conditional commitment letter.
In competitive housing markets, home sellers prioritize offers backed by genuine pre-approvals because they carry far lower financing risk. Securing pre-approval before touring houses also locks in an objective price ceiling, preventing you from pursuing properties outside your realistic budget.
Step 4: Save for Down Payment and Closing Costs
Beyond the down payment, buyers must budget for closing fees, which typically run between 2% and 5% of the total loan amount. These fees cover home appraisals, title searches, loan origination charges, upfront insurance premiums, and initial property tax escrow funds. First-time buyers frequently exhaust their savings on the down payment, forgetting closing expenses; explore local municipal grants that help cover closing costs.
Step 5: Shop for Homes Within Your Approved Budget
Partnering with a licensed real estate buyer’s agent provides local neighborhood data, pricing history, and contract negotiation support at no direct expense to you in most conventional sales. Remain strictly disciplined within your pre-approved price range during tours to avoid emotional attachment to homes that strain your finances after factoring in property taxes and maintenance.
Step 6: Submitting an Offer and Navigating Purchase Contingencies
Your formal purchase contract should contain standard protective contingencies: a financing contingency (permitting withdrawal if loan underwriting fails), an inspection contingency (allowing cancellation or repair negotiations based on structural flaws), and an appraisal contingency (safeguarding your earnest money if the property appraises below the agreed sale price). Avoid waiving these vital protections without understanding the financial risks.
Step 7: The Underwriting and Home Appraisal Process
Once the purchase agreement is ratified, your lender schedules an independent appraisal to confirm property value and initiates underwriting review. Underwriters routinely request supplemental paperwork, such as explanations for large account transfers or updated pay stubs. Responding immediately keeps closing on schedule. Avoid changing jobs, taking out new credit lines, or financing major purchases during underwriting, as this can derail loan approval.
Step 8: Final Walkthrough and Signing on Closing Day
Shortly before closing, conduct a final walkthrough to confirm the property’s condition and verify that agreed repairs were completed properly. On closing day, you will review your final Closing Disclosure (which should mirror your Loan Estimate), execute closing paperwork, and wire your down payment and closing funds. Once deeds are recorded, you receive the keys to your new home.
Common First-Time Home Buyer Mistakes to Avoid
- Applying with only one lender instead of comparing multiple official Loan Estimates.
- Financing furniture or opening retail credit cards while the mortgage is in underwriting.
- Focusing solely on principal and interest while ignoring taxes, hazard insurance, and HOA dues.
- Waiving the home inspection to make an offer competitive, risking expensive hidden structural flaws.
- Failing to check municipal and state down payment assistance grant programs.
Private Mortgage Insurance (PMI): How It Works & How to Remove It
Conventional mortgages with less than 20% down require Private Mortgage Insurance (PMI), a monthly charge that protects the lender against default. On conventional loans, you can petition to drop PMI once your loan balance reaches 80% of the home’s value via principal payments or market appreciation.
Federal law mandates that lenders automatically cancel PMI once amortization reaches 78%. FHA loans differ, requiring mortgage insurance premiums (MIP) for the life of the loan in most cases unless you refinance into a conventional mortgage once equity reaches 20%.
Timing Your Mortgage Interest Rate Lock
Once under contract, you will secure a rate lock covering your expected closing window, typically 30 to 60 days. A rate lock insulates you against market rate spikes prior to closing. Inquire with your loan officer regarding lock extension fees if closing delays arise, and check if their policy includes a “float-down” option if rates drop.
Managing Homeowner Expenses After Closing
Homeownership brings expenses that renters do not pay, such as long-term property maintenance, which financial advisors estimate at 1% to 2% of the home’s value annually. Establishing a dedicated maintenance reserve account early ensures you handle unexpected appliance replacements or roof repairs without taking on high-interest credit card debt.
Working Alongside a Title Company or Real Estate Lawyer
Depending on local state real estate regulations, either a title company or a closing attorney oversees legal transfer, verifies clear title, and disburses escrow funds. Ask questions about title insurance coverage and deed filing to understand every document before signing.
Reviewing Your Mortgage Amortization Schedule
Studying your amortization schedule shows how early monthly payments are heavily weighted toward interest charges rather than principal paydown. Understanding this helps you appreciate how equity builds gradually, and highlights how making small extra principal payments shortens your overall loan term and saves thousands in total interest.
Frequently Asked Questions (FAQs)
How much do I actually need for a down payment as a first-time buyer?
It depends on the loan program. VA and USDA loans require 0% down, conventional first-time loans require 3%, and FHA loans start at 3.5%. Putting down 20% on conventional financing eliminates private mortgage insurance entirely.
How long does the entire home buying process typically take?
From an accepted purchase offer to closing typically takes 30 to 45 days. The preceding house-hunting phase varies from a few weeks to several months depending on housing inventory and your search criteria.
What credit score do I need to buy my first home?
FHA loans accept scores down to 580 with 3.5% down (and 500 with 10% down). Conventional mortgages generally require a 620 minimum, with the most favorable interest rate pricing reserved for scores of 740 and above.
The Bottom Line
Purchasing a first home involves numerous moving parts, but breaking the transaction into sequential phases—calculating true affordability, selecting the ideal loan program, securing pre-approval, saving for closing costs, and remaining disciplined during underwriting—makes the journey completely manageable. Preparing your credit and savings months before searching ensures you make strong, confident offers when the right property appears.