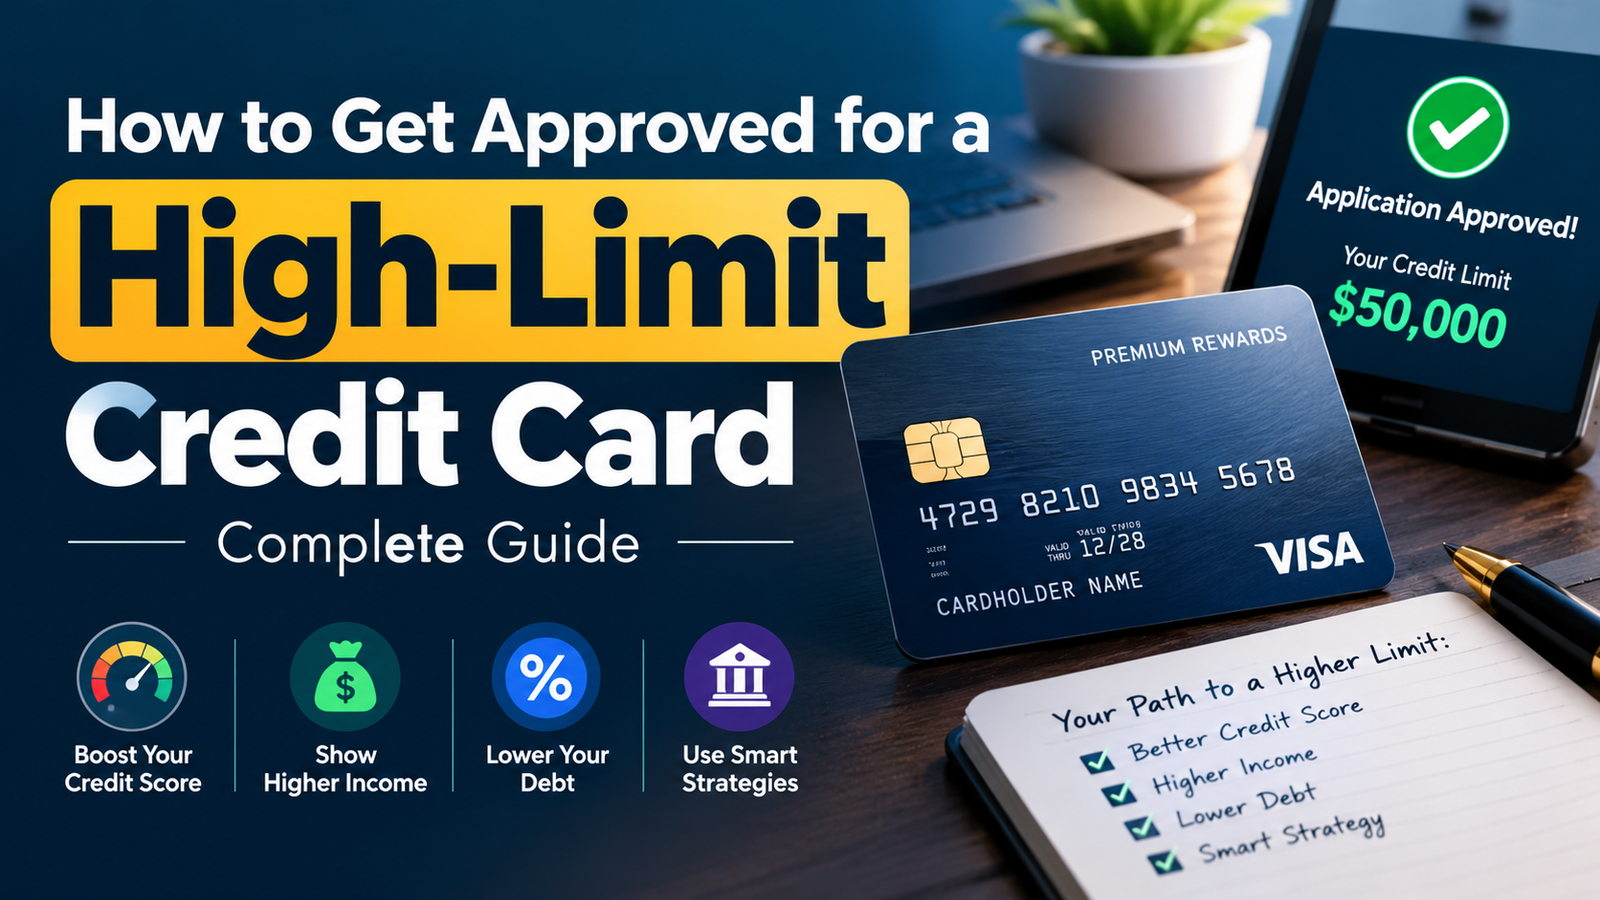

A high-limit credit card delivers greater purchasing power, added flexibility for large emergency expenses, and a lower credit utilization ratio that can directly enhance your credit score. However, qualifying for a substantial credit line requires understanding what bank underwriting models look for beyond just a good credit score.
This guide breaks down the core factors that influence credit limit determinations, how to strategically position your finances for a high-limit approval, and practical steps to take if an approved card comes with a lower limit than you expected.
What Factors Actually Determine Your Credit Limit?
Card issuers establish credit limits based on a combination of your credit scores, verified annual income, current debt payments, length of credit history, and your existing banking relationship with that specific institution.
Annual income is especially critical for limit amounts, independent of your credit score. For instance, two applicants with identical 780 credit scores but vastly different salary levels will often receive substantially different credit limits, as banks use income to assess your capacity to service recurring debt payments.
The Impact of Your Debt-to-Income (DTI) Ratio
Beyond checking credit scores, banks evaluate your debt-to-income (DTI) ratio by comparing your monthly gross income against existing recurring obligations—including auto loans, student loans, mortgage or rent payments, and minimum card balances.
Carrying high existing debt relative to your income can prompt an issuer to approve a modest credit limit even if your credit score is in the excellent range, as the bank must manage its total risk exposure across all your open credit lines.
| Underwriting Factor | Direct Impact on Credit Limit Decisions |
|---|---|
| Credit Score | Higher tiers (740+) unlock top-tier initial credit limits |
| Reported Income | Directly sets the ceiling on maximum credit an issuer will extend |
| Existing Debt Load | High debt-to-income ratios reduce approved credit lines |
| Credit History Age | Longer histories with zero missed payments support higher approvals |
| Bank Relationship | Existing checking or lending customers often receive higher offers |
How to Build Toward a High-Limit Approval
Maintaining an unblemished on-time payment track record across all open accounts is the single most vital factor, as payment history carries the heaviest weight in credit scoring formulas.
Keep your revolving credit utilization below 30%—and ideally under 10%—across all cards to demonstrate responsible debt management. Additionally, allowing existing accounts to age naturally without opening multiple accounts in quick succession demonstrates long-term stability to prospective lenders.
Requesting a Credit Limit Increase on Current Cards
Rather than always submitting new card applications, asking for a credit limit increase on a card you have managed well for over six months is often a faster, lower-risk strategy. Many major card issuers handle limit increases via simple online dashboard forms that frequently use soft inquiries without hurting your credit score.
Be ready to submit updated annual income figures during your request. If your salary has grown since you first opened the card, providing this new data helps the bank’s automated systems justify a substantially larger credit line.
Premium Cards and Charge Cards With Higher Limits
Certain card categories are structured with high baseline limits or no preset spending limits, such as luxury charge cards that require balances to be cleared monthly. These accounts typically demand strong credit scores and substantial income to qualify, and often feature annual fees justified by premium travel perks, lounge access, and elevated rewards rates.
Steps to Take If Your Approved Limit Is Lower Than Expected
- Build a 6-Month Track Record: Make consecutive on-time payments and maintain low balances for at least six months before requesting a limit bump.
- Update Your Income Profile: Ensure your bank has your latest compensation numbers on file, especially if you have had raises or bonuses.
- Pay Down Other Credit Card Balances: Lowering debt on other cards reduces your overall DTI ratio, making you look less leveraged.
- Request a Credit Line Reallocation: If you hold multiple cards with the same bank, call customer service and ask to shift available credit from an older card to your new one.
How a Higher Credit Limit Impacts Your Credit Score
Assuming your monthly spending habits stay consistent, a higher total credit limit directly lowers your overall credit utilization percentage (the ratio of debt to available credit). Because utilization is one of the most influential factors in credit scoring, getting an approved limit increase frequently triggers an improvement in your credit score during the subsequent reporting cycle.
Potential Risks of Having a High Credit Limit
A substantial credit limit can make overspending tempting if budgeting habits are loose. A large credit line removes the automatic spending guardrail that a smaller limit naturally provides. It is important to treat your credit limit as an emergency cushion and utilization buffer rather than disposable spending money.
How Banks Automatically Re-Evaluate Your Limit
Beyond direct customer requests, most card issuers periodically conduct automated account audits. Cardholders who routinely use their cards, pay on time, and maintain low revolving debt often receive automatic, unprompted credit limit increases through the bank’s internal risk management reviews.
Managing Multiple Credit Cards for Maximum Available Credit
Rather than focusing all efforts on a single card, maintaining several accounts across two or three different banks allows you to amass a much higher cumulative credit line. This approach also provides practical redundancy if one card is temporarily locked due to suspected fraud.
Joint Applications and Co-Signer Considerations
A few institutions still allow joint credit card accounts, which evaluate combined household incomes and credit profiles to grant higher limits. However, because both parties become fully liable for any unpaid debt, most modern banks prefer individual primary accounts with authorized user designations instead.
How Seasonal or Variable Income Affects Limit Decisions
Self-employed workers, freelancers, or commission-based earners may encounter conservative credit limit offers due to variable monthly cash flow. Providing tax returns and bank statements reflecting consistent earnings over multiple years helps overcome conservative automated underwriting limits.
Diversifying Available Credit Across Multiple Banks
Instead of trying to secure a single card with an enormous limit, focusing on your aggregate available credit across all cards provides the same credit utilization benefit while spreading your relationship across different financial institutions.
Evaluating High-Limit Cards With Annual Fees
Premium cards that offer high starting limits often carry annual membership fees. Make sure the value of travel credits, companion passes, and rewards categories legitimately offsets the cost of the fee before applying simply for a higher credit limit.
Using a High Limit for Balance Transfers
A newly approved high-limit card can be an effective destination for consolidating high-interest balances from older cards, provided it features a 0% introductory APR window on balance transfers. This strategy merges a large credit ceiling with immediate interest savings.
Psychological Impacts of Having a Higher Credit Limit
Behavioral finance studies show that higher available credit can subconsciously influence spending choices. Maintaining internal personal spending limits independent of your card’s credit ceiling keeps your finances anchored to your actual cash flow.
Managing a Large Credit Line Responsibly
A substantial credit limit is an asset when combined with personal budgeting discipline and automatic full monthly payments. Taking an honest inventory of your spending habits ensures that pursuing higher limits supports your wealth-building goals.
Staying Informed on New Card Offers
Credit card rewards structures and underwriting terms change regularly as lenders compete for prime borrowers. Periodically reviewing current market offers helps you identify better rewards rates and higher starting lines as your credit profile matures.
Final Thought
A high credit limit is a practical financial tool rather than a status symbol. Its true benefit lies in lowering credit utilization, strengthening your credit score, and providing flexible peace of mind for genuine financial emergencies.
Frequently Asked Questions (FAQs)
Does requesting a credit limit increase hurt my credit score?
It depends on the card issuer. Many major banks process online credit limit requests using a soft inquiry that does not affect your score, while others perform a hard credit pull. You can confirm which type of inquiry will be used before submitting the request.
How often can I request a credit limit increase?
While bank policies vary, spacing credit limit increase requests at least six months apart is standard practice. Submitting repeated requests over a short period can trigger automated risk flags with your lender.
Is a higher credit limit always better for my credit score?
Generally yes, because it lowers your credit utilization ratio. However, the score benefit only holds true if your monthly spending remains consistent and you do not accumulate new debt matching the higher limit.
The Bottom Line
Securing a high-limit credit card requires demonstrating consistent on-time payments, maintaining low debt utilization, and reporting accurate income figures. Whether you apply for a new premium rewards card or request an increase on an existing account, building strong financial fundamentals is the most dependable way to earn and keep a substantial line of credit.