When Do You Need an Estate Planning Lawyer: Wills, Trusts, and the Probate Process

Many individuals put off estate planning because they think they lack enough wealth to warrant it, or simply because discussing mortality feels uncomfortable. However, passing away without a clear plan can force families into prolonged, costly probate proceedings and disagreements that a modest upfront investment in legal guidance could have easily prevented.
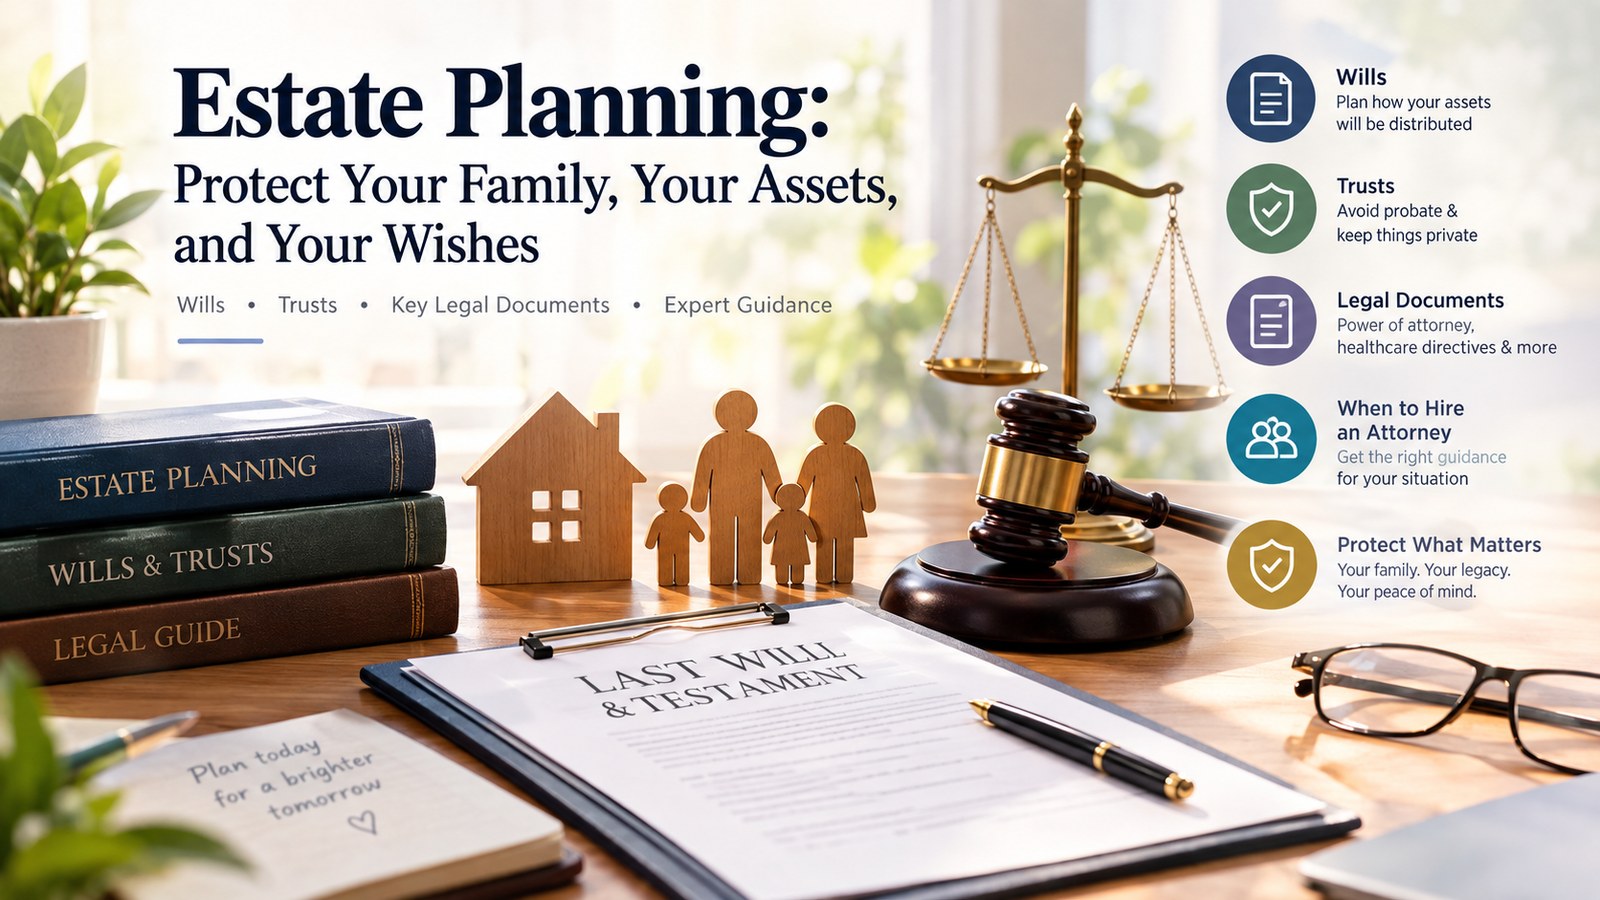
This guide outlines when hiring an estate planning attorney is truly necessary, clarifies the difference between a will and a trust, and breaks down the core legal documents most families genuinely require.
Wills vs. Trusts: Understanding the Main Differences
A will is a legal document outlining how your property should be distributed upon death and naming guardians for minor children. However, assets transferred through a will typically must pass through probate—a court-supervised procedure that can take several months or longer and incurs court costs and legal fees deducted from the estate.
In contrast, a trust—especially a revocable living trust—enables property held in the trust’s name to transfer directly to beneficiaries outside of probate. This generally ensures a quicker and more confidential transfer, although establishing a trust requires more initial legal preparation and upfront expense than drafting a basic will.
When Is a Simple Will Enough?
For people with modest estates, no real estate beyond their primary residence, and uncomplicated wishes regarding inheritance, a well-prepared will paired with basic supplementary documents is usually plenty.
This holds especially true in jurisdictions offering streamlined or expedited probate for small estates, where the delays and expenses of probate are far less burdensome than they would be for a large, intricate estate undergoing formal court administration.
When Does a Trust-Based Plan Make More Sense?
Individuals with substantial wealth, property located across multiple states (which can trigger separate probate cases in each state), or a strong preference for privacy—since probate files are public record while trusts remain private—usually benefit much more from a trust-based strategy.
A trust is also ideal if you anticipate family disputes or have an heir who requires protected, gradual distributions. Furthermore, business owners frequently rely on trusts to guarantee operational continuity and shield company assets from the delays of probate court.
| Family / Financial Situation | Likely Best Solution |
|---|---|
| Modest estate, straightforward wishes | A will-based plan is usually sufficient |
| Owning real estate in multiple states | A trust prevents multi-state probate proceedings |
| Parents with minor children | A will for guardian nomination plus a trust for financial management |
| Business owners | A trust combined with a business succession agreement |
| Beneficiary needing financial protection | A trust with staged or supervised payouts |
Essential Legal Documents Beyond a Will or Trust
- Durable Power of Attorney: Gives a trusted person legal authorization to manage your finances if you become incapacitated.
- Healthcare Power of Attorney (Healthcare Proxy): Appoints someone to handle medical decisions on your behalf if you cannot speak for yourself.
- Living Will (Advance Directive): Clarifies your personal preferences regarding life support and end-of-life treatments.
- Beneficiary Designations: Updated designations on retirement funds and life insurance policies that transfer independently of a will or trust.
Why Beneficiary Designations Can Override a Will
Many people assume a will oversees the distribution of all their possessions. However, retirement accounts, life insurance policies, and payable-on-death (POD) bank accounts transfer directly to whoever is named on the form, regardless of what your will states.
This means an outdated beneficiary form—such as a former spouse listed prior to a divorce—will override the instructions in a newly written will. An estate attorney must review these forms alongside your documents to prevent costly discrepancies.
Estate Tax and Inheritance Tax Rules
Federal estate taxes only apply to very large estates exceeding high statutory exemption thresholds, meaning the vast majority of families will never owe federal estate taxes. However, because these thresholds can shift with new laws, periodic reviews are recommended if your assets grow close to the limits.
Additionally, some individual states collect their own estate or inheritance taxes with noticeably lower exemption caps. A local attorney will help you navigate state-specific tax laws if you reside in or own assets in one of these jurisdictions.
How Estate Planning Lawyer Fees Are Structured
Basic wills and standard medical/financial directives are frequently billed as a flat fee due to their straightforward nature. Trust-based packages and complex arrangements—such as business transitions, blended family terms, or tax strategies—usually carry higher flat fees or hourly rates due to the additional customization required.
Asking for a clear upfront fee breakdown and confirming what post-drafting support (like future amendments or reviews) is included ensures an open, comfortable working relationship.
The Hidden Costs of Dying Without an Estate Plan
Dying without a will is called dying “intestate.” In these cases, state law decides who inherits your assets, which may not align with your true wishes and often creates avoidable tension among surviving relatives.
Beyond the emotional strain, intestate estates face slower and more expensive court proceedings. Crucially, without a nominated guardian, a family court judge decides who raises minor children without parental input—making basic planning critical for young families.
When Should You Update Your Estate Plan?
Your documents should be re-examined after major milestones, including getting married, divorcing, having a child or grandchild, experiencing a big change in assets, moving to a new state, or the passing of an appointed executor or trustee.
Most legal professionals also recommend a routine review every three to five years, as personal priorities and state statutes gradually shift over time.
Selecting the Right Executor or Trustee
The person or institution chosen to act as executor of your will or trustee of your trust carries real legal obligations: settling debts, handling tax filings, managing assets, and resolving any conflicts among heirs.
Select someone who is dependable, organized, and willing to take on the responsibility. Discussing the position with them in advance prevents confusion and ensures they feel ready to manage the estate.
Managing Digital Assets in Modern Estate Planning
Modern estate planning increasingly includes digital property: online banking, cryptocurrency wallets, cloud storage, email, and social profiles. Traditional boilerplate forms drafted years ago often overlook these accounts.
An estate lawyer can integrate specific digital asset clauses so that your executor has legal authorization and practical instructions to access and manage these accounts.
Coordinating Life Insurance With Your Estate Plan
Life insurance proceeds bypass probate and go directly to listed beneficiaries. Because minors legally cannot inherit substantial funds directly, lawyers frequently suggest setting up a trust to receive policy payouts for young children, avoiding court-appointed guardianship over the funds.
Special Needs Trusts for Dependents With Disabilities
Families caring for a dependent with special needs require careful legal planning. A special needs trust can provide financial support for supplemental care without disqualifying the individual from government programs such as Medicaid or SSI.
Using a No-Contest Clause to Prevent Disputes
Some planners add a “no-contest” clause to wills and trusts. This rule states that if any beneficiary challenges the validity of the document and loses, they forfeit their inheritance entirely—helping deter family litigation.
Integrating Business Succession With Personal Estate Planning
Company founders need plans detailing how ownership transitions if an owner passes away or becomes unable to work. Using buy-sell agreements funded by life insurance ensures the company continues running smoothly without becoming tangled in personal probate proceedings.
The Advantage of Maintaining a Long-Term Attorney Relationship
Working with the same estate planning lawyer over several years creates continuity. Because they already know your family background and financial history, updating your documents as your life changes becomes faster and much simpler.
Taking the First Steps Toward an Estate Plan
Booking an initial consultation is the most practical starting point, even if you are not sure which legal documents you need. A good lawyer will review your goals and suggest an approach that matches your budget and circumstances.
Reviewing Your Estate Plan When Laws Change
State and federal laws are updated periodically. An estate plan created a decade ago might not take advantage of new tax rules or statutory protections, making periodic check-ins worthwhile.
Final Thought
Ultimately, an estate plan is a thoughtful gesture for the loved ones you leave behind, sparing them confusion, legal hurdles, and unnecessary costs during a grieving period.
Frequently Asked Questions (FAQs)
Do I need an estate planning lawyer if I don’t have significant wealth?
Yes, especially if you have young children who need legal guardians named. Even smaller estates benefit from basic legal documents that avoid probate delays and guarantee your personal choices are honored.
Can I write my own will without a lawyer?
While DIY templates are legally valid in most states, they carry risks of execution errors, unclear wording, or missed state rules. Correcting mistakes in probate court after death is often far more expensive than hiring an attorney initially.
How often should I update my estate plan?
Review your documents after major life milestones (marriage, divorce, new children, or moving states). In the absence of big events, a standard review every three to five years is recommended.
The Bottom Line
Estate planning is not reserved solely for the wealthy. Anyone with children, modest savings, or strong preferences about future healthcare choices benefits from working with a qualified estate planning lawyer. Knowing whether you need a simple will or a living trust, keeping beneficiary records updated, and reviewing documents regularly ensures your true wishes—not state intestacy statutes—direct your family’s future.